People don’t think about long-term care until they need it. But now is the perfect time to act.
What is Long-Term Care Insurance?
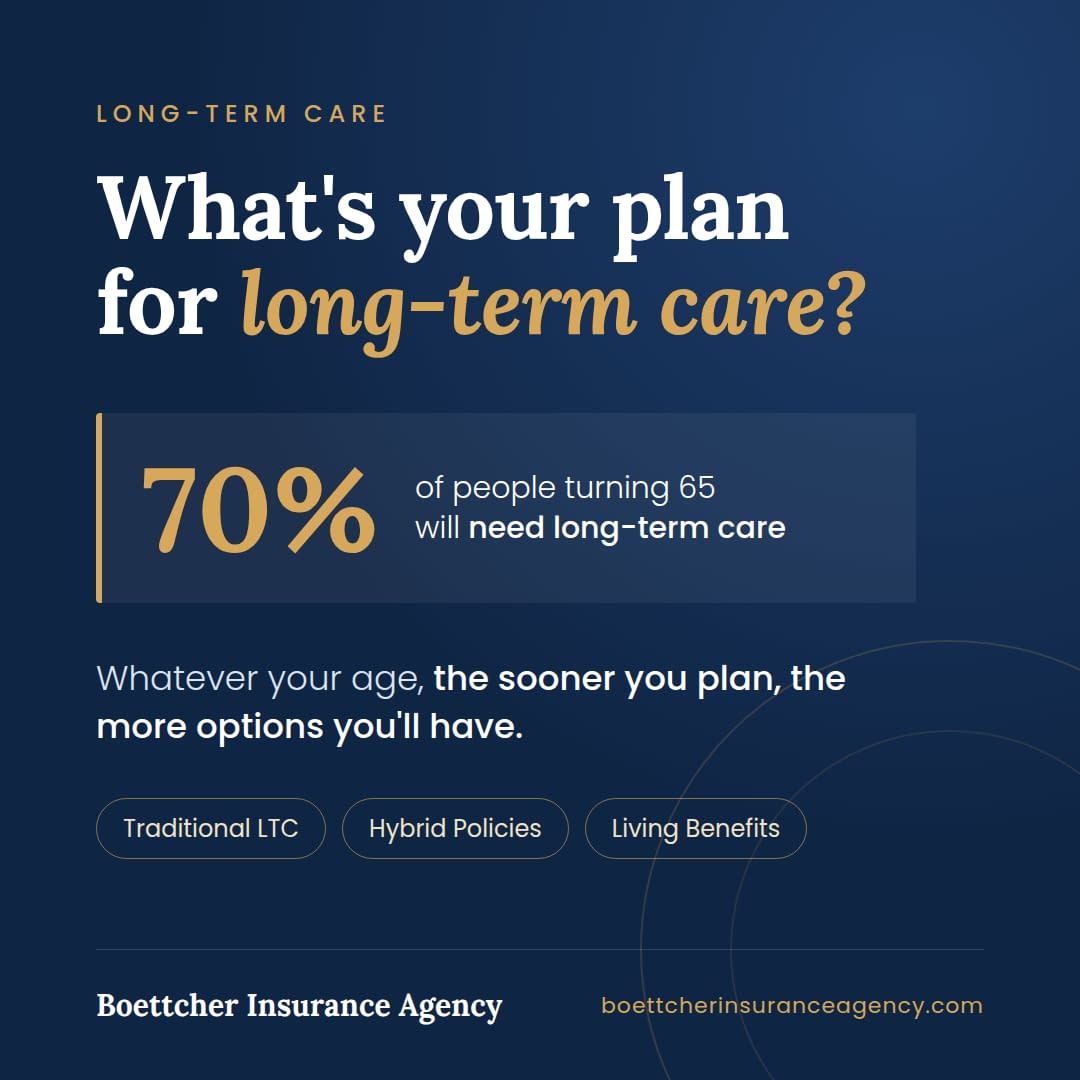
Long-term care (LTC) insurance helps pay for in-home care, assisted living, or a nursing home when illness, injury, or cognitive decline makes everyday tasks hard to manage. Health insurance and Medicare cover little; about 70% of people turning 65 will need long-term care.
Ask yourself: How would you pay for long-term care if it cost $300,000 to $500,000? Where would that money come from? A few years of care can reach that range — and you don’t have to cover it alone.
Why Planning Pays Off
Your health and your age set your price, and both work in your favor the sooner you act
Lower premiums — Waiting 10 years can raise the cost of the same coverage by 30–50% a year.
Easier to budget — adding a premium while you’re earning is far simpler than doing it in retirement.
Consider a Hybrid Policy
Hybrid policies combine LTC benefits with life insurance or an annuity — if you never need care, your beneficiaries receive a death benefit instead.
Accelerated Living Benefits
Add an accelerated living benefit (ALB) rider to your life insurance, and you can tap part of your death benefit early if you’re diagnosed with a chronic, critical, or terminal illness to use however you need, whether that’s medical bills, in-home care, or lost income. Many carriers include it at little or no extra cost, and any unused portion passes as a death benefit.
ALB isn’t a full LTC substitute— but it’s an affordable layer of protection.
Whatever your age, the best time to plan for long-term care is before you need it. The sooner you start, the more options you’ll have, whether that’s a traditional LTC policy, a hybrid, or life insurance with accelerated living benefits.